
Are collectibles good long-term investments? In their September 2013 paper entitled “The Investment Performance of Emotional Assets”, Elroy Dimson and Christophe Spaenjers estimate long-term returns for selected collectibles and review the risks associated with such investments. They focus on art, stamps and violins, and also consider wine and diamonds. Using repeat sales histories and catalog prices for aesthetic investments, along with contemporaneous returns for UK equities, UK government bonds/bills and gold, during 1900-2012, they find that:
- Over the sample period, the gross annualized nominal (real) returns for art, stamps and violins are in the range 6.4%-6.9% (2.4%-2.8%). Annualized gross real returns for equities, government bonds/bills and gold over the same period are 5.2%, 1.5%/0.9% and 1.1%, respectively.
- Standard deviations of nominal returns for art, stamps and violins are 13.2%, 13.5%, and 10.1%, respectively, compared to 11.9% for government bonds and 21.6% for equities. However, raw standard deviations underestimate the actual volatility of collectibles returns due to infrequent transactions.
- Pairwise return correlations among collectibles are not large, and those between collectibles and equities are low. However, correlations with prior-year equity returns indicate a relationship between equity market wealth and future prices of collectibles.
- Transaction costs in collectibles markets are high (such as 25% for stamps). Moreover, collectibles bear unquantified storage costs and risks of fluctuating tastes (survivorship bias in return estimates) and fraud.
The following chart, taken from the paper, compares gross real cumulative performances of collectibles and financial asset indexes during 1900 through 2012,with each index normalized to 1 at the beginning of 1900.
Collectibles outperform government bonds/bills and gold, but underperform equities on a gross basis. However, the very high trading frictions and other costs for collectibles may offset any gross returns.
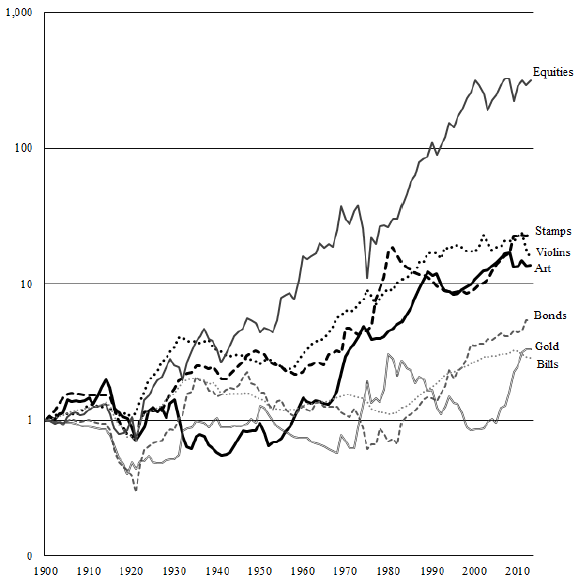
In summary, evidence suggests that selected collectibles held over very long periods may be competitive with government bonds and bills, but not equities.
Cautions regarding findings include:
- As emphasized in the paper, the “headline” returns are gross. Including the large trading frictions and other costs involved in buying, holding and selling collectibles may eliminate returns.
- As noted in the paper, the survivorship bias associated with focusing on selected “high-quality” collectibles with long histories (ignoring fad collectibles that continually disappear from the market) may be substantial.
- Acquiring and maintaining an inventory of collectibles representative of the indexes used in the study is beyond the reach of most investors.
Frequently Asked Questions
What are emotional assets or collectibles in investing?
Emotional assets, or collectibles, are aesthetic investments such as art, stamps and violins (and also wine and diamonds) that are held partly for the enjoyment they provide as well as for financial return. In the Dimson and Spaenjers study, their long-term returns were estimated from repeat sales histories and catalog prices over 1900-2012 and compared with UK financial assets.
Do collectibles like art, stamps and violins outperform stocks over the long term?
No, collectibles such as art, stamps and violins underperformed UK equities on a gross basis over 1900-2012. Their gross annualized real returns were 2.4%-2.8%, versus 5.2% for equities, though they beat government bonds/bills (1.5%/0.9%) and gold (1.1%). High transaction costs may eliminate even these gross returns.
How are long-term returns on collectibles like art and stamps measured?
Long-term collectibles returns are measured using repeat sales histories (the same item sold more than once) and catalog prices, then compared with contemporaneous UK equity, government bond/bill and gold returns. The Dimson and Spaenjers study applied this approach over 1900-2012, reporting gross annualized nominal returns of 6.4%-6.9% for art, stamps and violins.
How do collectibles compare with stocks, bonds and gold in risk and diversification?
Reported standard deviations of nominal returns for art, stamps and violins (13.2%, 13.5%, 10.1%) are below equities (21.6%) and similar to government bonds (11.9%), but infrequent transactions mean these figures understate true volatility. Correlations among collectibles and between collectibles and equities are low, though collectibles prices relate to prior-year equity returns, indicating a link to equity market wealth.
What are the risks and limitations of investing in collectibles?
Collectibles investing faces high transaction costs (such as 25% for stamps), unquantified storage costs, fraud risk and changing tastes, and the headline returns are gross of these costs. Survivorship bias from focusing on selected high-quality collectibles with long histories may be substantial, and replicating the study's indexes is beyond the reach of most investors.